Earlier this fall, we published our annual research report, “Insurance Operations in a Changing Industry,” which is based on survey results from nearly 400 global insurance executives. Working on behalf of Earnix, Market Strategy Group, LLC surveyed these insurance executives in a wide range of roles and departments, including C-level, IT, analytics, product, pricing, and underwriting.
The sample represented insurance companies from Europe and Australia as well as the United States and Canada and included a balanced mix of insurers with less than 20,000 employees as well as those with more than over 20,000 employees.
We’ve written some blogs (and infographics) that highlight important findings from the research. More specifically, insurers’ views on topics such as personalization, a new focus on profitability, climate change, and even a look at how changing economic conditions will shape their business in the year ahead.
Yet there’s so much good information in this report that we wanted to provide a closer look at five insurance industry statistics. (To learn even more, please download the full report now).
1. Cybersecurity is Now a Top Concern
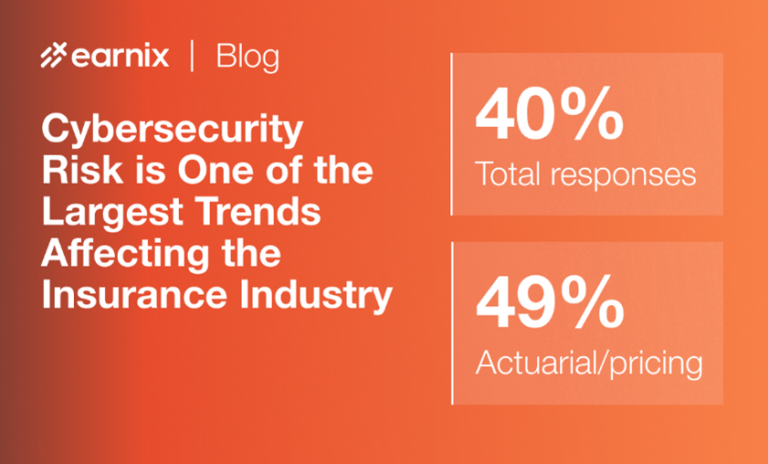
According to the research findings, “growing cybersecurity risks” are now the most significant trend confronting the entire insurance industry. A total of 40% of research respondents cited this as their top concern – making it #1, even over other trends such as AI, climate change, and the economy.
Additionally, 49% of actuarial and pricing executives ranked cybersecurity risks as their most important trend.